Profit is not the same as cash in the bank
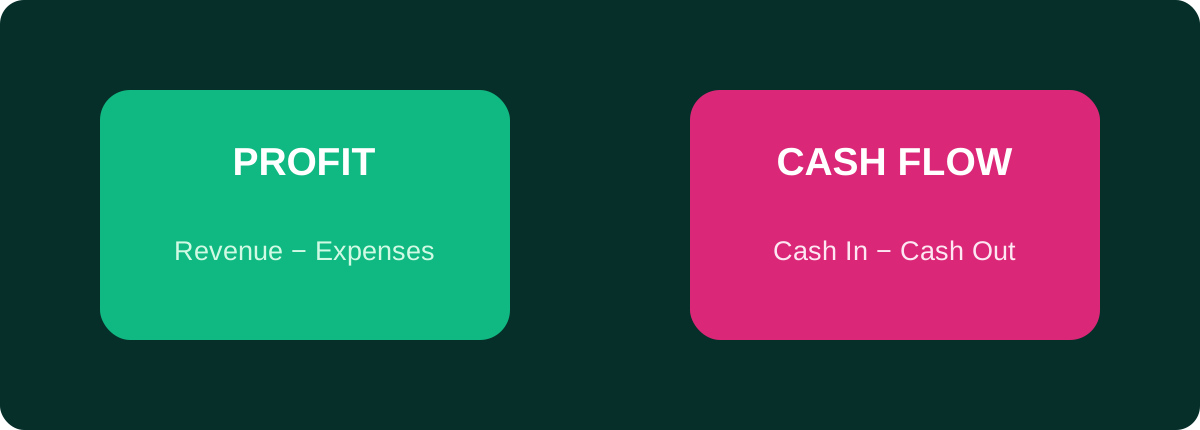
A company may record a profitable sale even though the customer has not paid yet.
Profit appears in reporting while cash has not arrived.
Credit customers
Growing credit sales can increase reported profit while cash remains tied up in receivables.
Buying too much inventory
Cash invested in inventory has not disappeared, but it is no longer immediately available for daily operations.
Supplier and financing payments
Profitable businesses can still use significant cash to settle suppliers, loans and earlier obligations.
Capital expenditure
Equipment, vehicles and other assets can consume cash without appearing as a full expense in the same accounting period.
What should management monitor?
- ✓ Customer receivables and ageing.
- ✓ Collection dates.
- ✓ Slow-moving inventory.
- ✓ Incoming and outgoing cheques.
- ✓ Supplier obligations.
- ✓ Expected cash flow.
- ✓ Actual bank balances.
Connected systems provide better visibility
When sales, receivables, inventory, cheques and accounting are connected, management can explain the difference between profit and available cash.